Behind on your mortgage? See your real options in 60 seconds.
Enter a few numbers to see what a sale would leave you with, what staying could look like, and what to ask your servicer about.
- No credit check and no obligation
- Licensed agent and licensed general contractor
- Your information stays private
If you sell now
If you stay
If home prices in your area grow:
What it would look like if you sold at each point:
Estimates only. Home worth grows at a year. We subtract 6% for selling costs and keep your loan balance the same. Paying down your loan would help slightly.
Where you stand
Want help making sense of these numbers?
A licensed agent will go through them with you for free. No pressure.
Modify: options to ask your servicer about
Availability depends on your loan type and your servicer. We help you ask the right questions.
Forbearance or repayment plan
Your servicer pauses or reduces payments for a set period, then you catch up over time. Best when the hardship is temporary.
Loan modification
The servicer changes your rate, term, or balance to lower the payment for good. Best when the hardship is lasting.
Partial claim and other programs
FHA and VA loans may offer a partial claim or a special program that moves missed payments to a second lien. Ask which programs apply to your loan type.
Sell as is, or let us renovate first.
A tired house sells for less. As a licensed agent and a licensed general contractor, we handle the repairs and the listing together.
When a renovation makes sense for your home, there is no upfront cost to you. LiveWell Homes fronts the approved costs and is reimbursed at closing. No lien is filed against your home, and there are no extra fees beyond a standard commission. We look at what your home could sell for after repairs, not only today's value. This works best when the sale leaves enough to reimburse the renovation. If it will not, we will tell you honestly.
- 1Free walkthrough. We scope the repairs and price the home as is and as renovated.
- 2We do the work. One team for the repairs, the staging, and the listing.
- 3Paid at closing. Approved renovation costs come out of your sale proceeds.
Short sale, foreclosure, or modification
| Question | Short sale | Foreclosure | Modification |
|---|---|---|---|
| Keep the home? | No | No | Yes |
| Who approves it? | Your lender must agree to accept less than the balance | Your lender starts and completes the process | Your servicer reviews your hardship application |
| Credit impact | Often smaller than a foreclosure | Often the largest and longest lasting | Varies by servicer reporting |
| Remaining balance | Get any waiver in writing | Depends on your loan and state rules | Not applicable |
What happens, and how much time you have
These are the general timelines for a standard California foreclosure. Your lender and loan type can change the details.
Missed payments
Federal rules generally keep a servicer from starting foreclosure until you are about 120 days behind. Your servicer should reach out to you about options first. This is the easiest time to ask about a repayment plan or a modification.
Notice of default
The lender records a notice of default with the county. This is the formal start of the foreclosure.
Three month wait
The lender must wait at least three months after the notice of default before it can schedule a sale. You can bring the loan current by paying what is owed plus fees.
Notice of trustee sale
The sale date is set at least 20 days after the notice is recorded and posted. You can still catch up on the loan until five business days before the sale.
Listing can buy time
Under a California law that took effect in 2025, an owner who signs a listing agreement with a licensed broker before the sale can request a one time postponement of about 45 days. Conditions apply, so ask us about the deadline.
Credit, taxes, and any remaining balance
Your credit
Each path affects your credit differently, and the effect depends on your history and how your lender reports it. Ask your servicer exactly how it will be reported.
Taxes
Forgiven debt can sometimes create a tax question. Talk to a tax professional before you sign anything that cancels part of your loan.
Any remaining balance
Whether you owe anything after a sale depends on your loan and what your lender agrees to. Get every waiver in writing, and consider a real estate attorney.
Ready to see your own numbers?
The calculator takes about 60 seconds and is free.
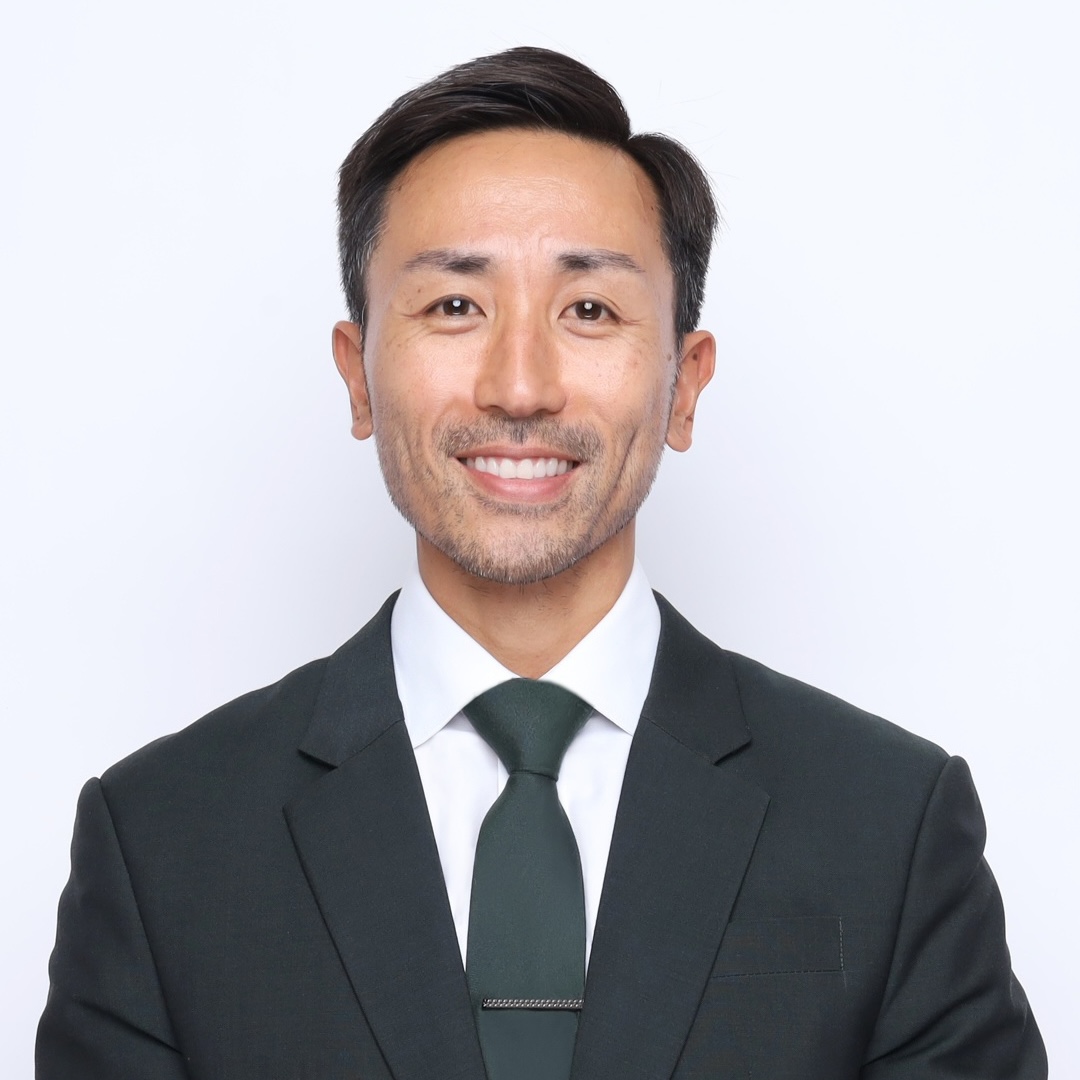
James Lee
I have helped homeowners through short sales, foreclosures, and tough sales since the last housing crisis. I am a licensed real estate agent and a licensed California general contractor, so I can price your home, plan the repairs, and manage the sale with one team.
I will walk you through every option, including the ones that do not involve me.
REALTOR, DRE #01862975. LiveWell Builds, CSLB #1148252. james@livewellhomesca.com
In their words
He helped us short sell our home during the Great Recession when nobody seemed able to help. I grew tired of dealing with the great faceless institutional bank. James took over and handled all the coordination and freed our family from the great stress. We are now living free of that burden and James is the reason. He cares!
Using James to sell my home was probably the single best decision made during the entire process. James has an expert understanding of the industry and how best to price and show a home to obtain the highest value. ... He also helped manage the entire process going above and beyond what would be expected of a real estate agent.
... from the very first meeting he began to make my life so much easier. I took every suggestion, made the improvements (which by the way, he coordinated every contractor for me!) ... But every time, he was right about his advice. ... We ended up getting $50K over asking and he did all the work.
I was in need to short sell my home and I had no clue how or who I could trust in this industry. ... James answered ALL of my questions and never kept me waiting. He made me feel extremely comfortable. ... He is truly an HONEST man just out to help you get back on your feet.
Client reviews, shortened for length. Individual results vary.
Get a free options review.
We look at your numbers with you and lay out every path, including the ones that do not involve us. No pressure.
- 1You send your numbers. It takes one minute.
- 2A real person calls within 24 hours. We review your options together.
- 3You decide. Sell, stay, or modify. There is no obligation.
Common questions
Does this hurt my credit?
Is this really free?
Do you charge any upfront fees?
Do I have to sell my home?
What if I owe more than my home is worth?
How soon do I need to act?
How accurate is my home value?
Who sees my information?
Want help that is not from us?
Free, approved housing counselors can review your situation, and your servicer has a hardship team you can call today.